Roofing industry guide
Roofing Contractor Financing: Materials, Deposits and Project Cash Flow
Roofers pay for materials and crews weeks before the final payment arrives, and weather can stretch that gap. Here is how to size it and match it to the right kind of financing.
Tell us about your jobs and supplier terms so an advisor can review options providers may offer.
 By Correia Financial
On this page
The short answer
Roofing financing usually comes down to one gap: paying for materials and crews before the customer pays. A line of credit or short-term working capital often fits that gap on residential jobs, invoice factoring can fit invoices owed by commercial customers and equipment financing fits trucks, trailers and hoists.
In California, deposits cannot cover much: a home improvement down payment is capped at $1,000 or 10 percent of the contract price, whichever is less. Size any financing to the gap on real jobs and test the payment against a rainy month.
Where the cash gap opens on a roofing job
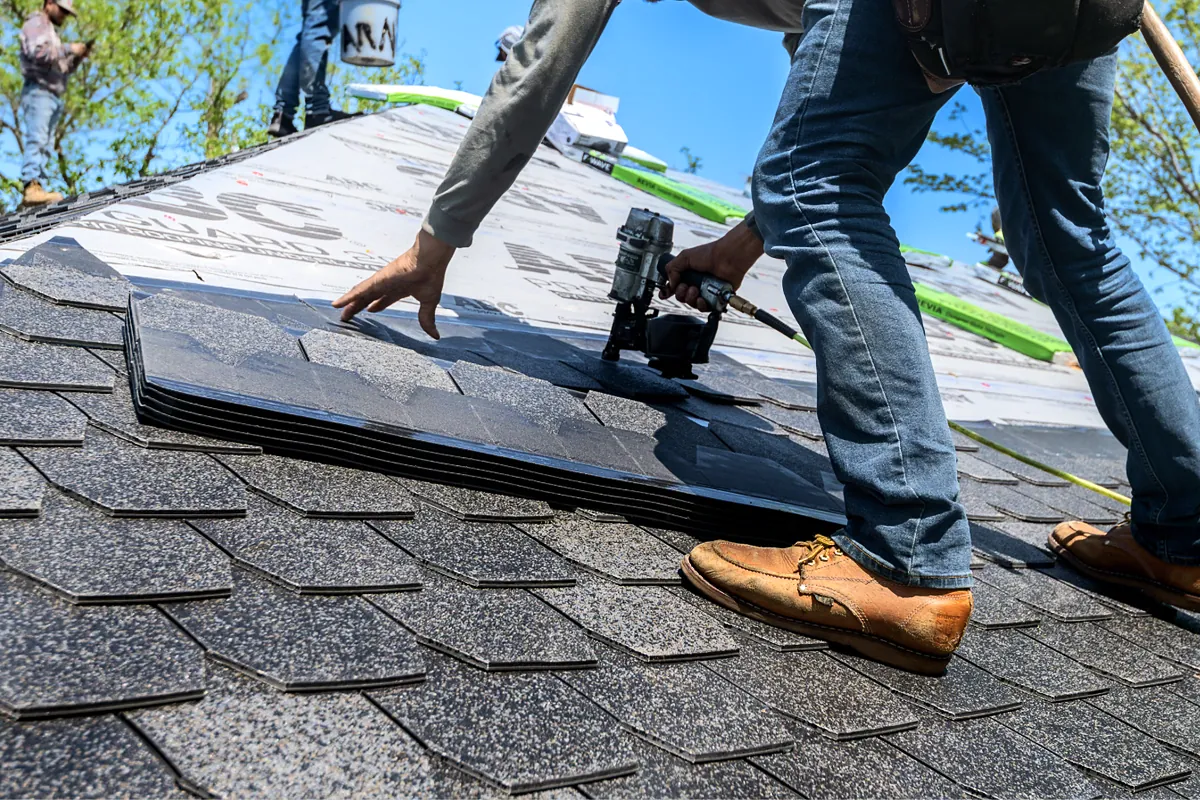
A reroof is paid for at the end and built at the start. The roofer buys shingles, underlayment and flashing, pays a crew for tear off and install and covers dump fees long before the customer’s final payment clears. The bigger the job, the longer and deeper that gap.
- Contract signedA deposit is collected, within any state limit.
- Materials orderedThe supplier invoice comes due on its own terms.
- Tear off and installThe crew is paid weekly, weather permitting.
- Final invoiceBilled after completion and any inspection.
- Payment and releasesThe customer pays, and lien releases are exchanged.
A general illustration. Timing varies by job, customer and contract.
Weather stretches the middle of that sequence. The Bureau of Labor Statistics notes that roofers usually do not work during bad weather, that work may slow in winter in northern states and that roofers may work overtime during the busy summer months. A week of rain pauses installs and billing, but the supplier’s due date does not move.
How much can a customer deposit cover?
In California, not much. For home improvement contracts, the Contractors State License Board says the down payment cannot be more than $1,000 or 10 percent of the contract price, whichever is less, and that there are no exceptions for special order materials.
Payments after the deposit are limited too. A CSLB industry bulletin reminds contractors that subsequent payments must not exceed the value of materials and work performed. In practice, a residential roofer in California funds most of the materials and early labor on a reroof from its own cash or from financing.
Hypothetical example: a $30,000 residential reroof in California
The contract price is $30,000. Ten percent would be $3,000, so the down payment is capped at $1,000. Materials cost $12,000 and the supplier expects payment within 30 days. Crew labor comes to $7,000, paid weekly.
If the only other payment is due at completion, the roofer carries about $18,000 ($12,000 plus $7,000, less the $1,000 deposit) until the customer pays. Two weeks of rain can push that payment past the supplier’s due date.
If the written payment schedule instead calls for a progress payment of $11,000 once materials are delivered, which stays within the value of materials delivered, the amount the roofer carries drops to about $7,000.
Hypothetical figures, not legal advice or a quote. Payment schedules must follow the law where you work; have your contract reviewed before you change it.
Outside California, deposit and payment rules differ by state, so check your own state’s home improvement rules before you build a cash plan around a larger deposit. Commercial roofing usually follows a different pattern: work is often billed through pay applications, and part of each payment may be held back until the end of the job.
Why supplier deadlines matter more than the invoice date
Paying your supplier on time protects more than your account terms. CSLB explains that an unpaid contractor, subcontractor, laborer or material supplier can file a mechanics lien against the property, and that the homeowner is ultimately responsible for payment even if they have already paid the direct contractor.
That is why property owners and general contractors often ask for lien releases before or when they pay. California’s waiver and release forms must substantially follow the forms in Civil Code sections 8132, 8134, 8136 and 8138. A conditional release on a progress payment is only effective if the claimant is actually paid, while an unconditional release states that payment has been received.
If your supplier is waiting on you, your customer may be waiting on your supplier’s release. A short delay in paying for materials can hold up your own final payment.
Financing that lets you pay the supplier when the invoice is due, and repay when the customer pays, protects both payments. If your supplier offers a discount for paying early, compare the discount with the cost of borrowing first; our guide to planning financing before a supplier discount deadline walks through the math.
Which financing fits each roofing cash need?
Roofing companies tend to need four different things, and each has a structure built for it. Providers decide what they will offer, and products vary.
Materials and crew on residential jobs
A business line of credit can be drawn when materials are ordered and repaid when the customer pays, then used again on the next job. It works best when it is in place before the busy season.
A one time push for a large job or a backlog
Short-term working capital can cover a defined gap. Some products collect daily or weekly payments, so check how they fit around weather holds.
Commercial invoices on payment terms
If you bill general contractors or property managers, invoice factoring turns approved invoices into cash before the customer pays. It is a sale of invoices, not a loan, and fees reduce what you collect.
Trucks, trailers and material hoists
Equipment financing spreads the cost of long-lived equipment over its useful life, with the equipment typically securing the financing.
How factoring works with your customers
When you factor an invoice, your customer is usually told to pay the factoring company. Under section 406 of Article 9 of the Uniform Commercial Code, once a customer receives notice that the amount has been assigned and that payment is to be made to the assignee, it can no longer discharge the debt by paying you. Expect your customers to see that notice, and expect the provider to look closely at the customers who owe you, not only at your business.
Many factoring providers focus on invoices owed by businesses. Whether a provider will buy invoices owed by homeowners, or tied to an insurance claim, depends on the provider. If one customer makes up most of your receivables, see factoring with one major customer.
Planning payments around rain delays and slow months
A fixed payment that is easy in a dry month can be hard in a wet one. Before you accept any offer, set its payments beside your weakest months, not your average month.
- Weekly deposits, dry month$20,000
- Weekly deposits, wet month$8,000
- Fixed weekly payment$2,500
Hypothetical round numbers for illustration. In the dry month the payment equals about 13% of deposits; in the wet month about 31%.
Payment frequency matters as much as the amount. A monthly payment gives you time to collect after a rain hold, while a daily or weekly payment starts drawing on the account right away. For more on matching payment timing to collections, see daily, weekly or monthly payments.
What providers may ask a roofing contractor
No single credit score, revenue level or number of years in business opens the door with every provider; each sets its own bar. Some providers restrict roofing or other construction trades, or ask for proof of licensing and insurance. Expect questions in two areas.
About your jobs
- What share of work is residential, commercial or insurance claim work?
- What deposit and progress payment terms do your contracts use?
- How many signed jobs are in your backlog, and when will they be billed?
- Who are your largest commercial customers, and how quickly do they pay?
About your cash
- How do deposits change between your busy and slow months?
- What do you owe suppliers, and on what terms?
- What loans, leases or advances are you already paying?
- Are any tax liens, judgments or mechanics liens open?
Documents to have ready
Start with your last four complete months of business bank statements, which the Correia application asks for. Depending on the request, a provider may also ask for signed contracts, supplier invoices, an accounts receivable aging, tax returns, a profit and loss statement and copies of your contractor license and insurance certificates. Our guide to business loan requirements covers each document.
How to compare the cost of each option
Line up every offer on the same terms: the funds you receive after any fees are withheld, the total you will repay or the total fees you will pay, the payment amount and frequency, the estimated APR and the collateral, UCC filing or personal guarantee the provider requires.
Reading a factoring disclosure
Under California’s commercial financing disclosure rules, many nonbank providers must give you a standardized disclosure for offers of $500,000 or less; for factoring, the threshold uses the approved advance limit. Because factoring costs depend on when your customer pays, the regulation uses an example transaction. The disclosure shows the funding provided, an APR, the finance charge with each expense included in it, a payment amount marked not applicable with an explanation, the estimated term and whether you may repurchase the invoice early.
If no part of the finance charge is interest, the disclosure must say the APR is not an interest rate. That is a useful reminder that factoring and revenue based financing are purchases, not loans, even though the APR helps you compare them with a line of credit.
For a deeper look at how fees and payment frequency change the real cost, see how to compare working capital costs.
When a roofing contractor may be better off waiting
Financing helps when it bridges a gap between costs you have already committed to and payments you can count on. It is a poor fit when the payment at the end is uncertain.
Consider waiting, or a smaller amount, when a job depends on an insurance claim that has not been approved, when the customer has not signed a contract with a clear payment schedule, or when the plan relies on stacking new advances to pay old ones. If your margins have not covered material price increases, raising prices or renegotiating supplier terms may help more than borrowing.
Correia Financial does not lend or set terms. As a brokerage, it looks at your jobs and cash flow and explores options with third party providers, and each provider makes its own credit decision.
Frequently asked questions
Can I take a larger deposit to cover roofing materials in California?
Not on a home improvement contract. CSLB says the down payment cannot be more than $1,000 or 10 percent of the contract price, whichever is less, with no exception for special order materials. Later payments must not exceed the value of materials and work performed.
Is a line of credit or working capital better for roofing materials?
A line of credit usually fits repeated material purchases, because you can draw, repay when the customer pays and draw again. Short-term working capital can fit a one time gap, but some products collect daily or weekly, which can strain cash during weather delays.
Can I factor invoices from homeowners or insurance claim jobs?
It depends on the provider. Many factoring providers focus on invoices owed by businesses, such as general contractors and property managers. Ask each provider which receivables it will consider before you apply.
Will my customers know I am factoring their invoices?
Usually, yes. Customers are typically notified to pay the factoring company, and under the Uniform Commercial Code (Article 9, section 406), once they receive that notice they can no longer pay you to settle the invoice.
Why does paying my supplier on time affect my own payment?
In California, an unpaid material supplier can file a mechanics lien against the property, and the owner can end up responsible even after paying you. Owners and general contractors often ask for lien releases before they pay, so a late supplier payment can delay your own.
What documents do roofing contractors usually need to apply?
Expect recent business bank statements first. Depending on the request, providers may also ask for signed contracts, supplier invoices, a receivables aging, tax returns, a profit and loss statement, your contractor license and insurance certificates.
Does Correia Financial lend the money?
No. Correia Financial is a brokerage that reviews roofing businesses and explores options with third party providers. Each provider makes its own credit decision and sets its own terms, and applying is no guarantee of approval or funding.
Sources
- Roofers, Occupational Outlook HandbookU.S. Bureau of Labor Statistics
- Learn About Home Improvement ContractsContractors State License Board, California
- CSLB Reminds Contractors of Progress Payment Restrictions (Industry Bulletin, November 2022)Contractors State License Board, California
- What is a Mechanics Lien?Contractors State License Board, California
- Conditional and Unconditional Waiver and Release FormsContractors State License Board, California
- Uniform Commercial Code, Article 9, Section 406: Discharge of Account Debtor; Notification of AssignmentLegal Information Institute, Cornell Law School
- Cal. Code Regs. tit. 10, § 913: Factoring Disclosure Formatting and Contents for Example TransactionsLegal Information Institute, Cornell Law School
- Cal. Code Regs. tit. 10, § 921: Thresholds for DisclosureLegal Information Institute, Cornell Law School
- California Financial Code § 22801: Commercial Financing Disclosures, exemptionsJustia
Sources reviewed October 12, 2026.